There are few things more satisfying for a small business owner than hearing the phone ring with a new order.
Perhaps today it is a construction company looking for transport. Tomorrow it is lunch for 30 workers. Next week, somebody needs uniforms, equipment repaired or materials delivered to a site.
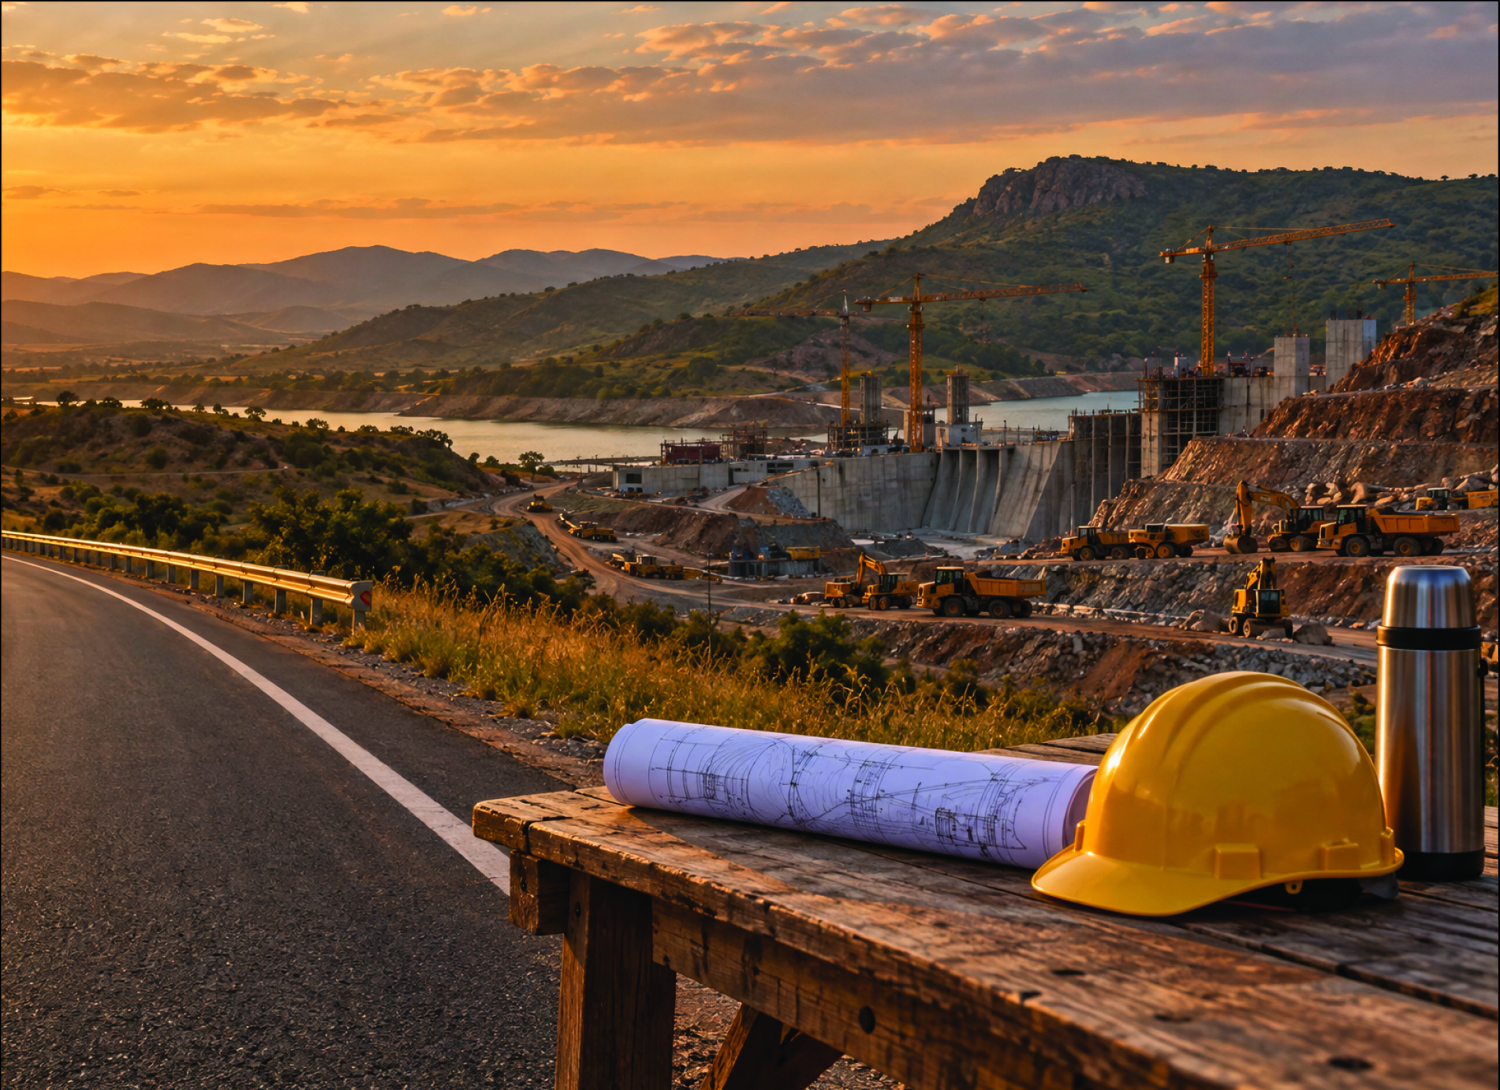
This particular business owner may never pour a bag of cement or operate an excavator. Yet somewhere nearby, a road is being upgraded, a dam is rising or a new building is taking shape, and some of the money being spent on it has found its way to their till.
This is how economic growth becomes tangible. Economists call it the multiplier effect: somebody else’s increased productivity becomes spending, that spending becomes your income, and part of yours becomes somebody else’s. Each round is smaller than the last, because some of every lilangeni leaks into savings, taxes and imports. In an economy that buys almost half of what it uses from South Africa and hands its big construction projects to foreign contractors, the leakage is nontrivial.
It is the first reason growth in our beloved kingdom is felt less than the headline suggests.
The headline is this. The ministry of economic planning and development’s September statement expects the economy to grow by 5.3% in 2026 and 4.1% in 2027, before growth averages about 2.6% between 2028 and 2031. It is the most optimistic reading on the table: the World Bank sees 3.9% this year and the IMF expects growth to moderate from last year’s 4.8%.
It helps to be clear about what is growing. GDP is the sum of everything the country produces in a year: every bag of cement, bus fare, sugar consignment and haircut, added together. Growth of 5.3% means that total is expected to be about four billion Emalangeni larger than last year’s.
That extra output is what becomes income, because every lilangeni of it is paid to somebody as a wage, a profit, a rent or a tax.
The growth rate is the speed. The extra output is the money. The question is who gets paid.
Five per cent is short of the 10 the minister of finance set as the ambition for this Parliament, but it is double the average of the past decade, and it sounds encouraging. It is also easy to misunderstand. Nobody receives 5.3% in a bank account. Salaries and turnover do not rise by the same amount. Growth arrives in particular sectors first, and the extra output takes time, often more than a year, to move through the economy before it shows up as income in our hands.
Of all the objectives we can set for ourselves as a country, economic growth is paramount, for more reasons than one. An economy that does not grow is untenable. One working-age person in three has no job and among the young more than one in two. Only an economy that needs more hands cures that, which means output growing faster than the population every year.
And it compounds. At the past decade’s 2.4% the economy doubles in about thirty years; at 5%, in fourteen. So 5.3% is worth wanting. The question this column asks is whether or not it reaches your pockets.
The September forecast maps where that movement should begin, and construction is the clearest place to look: Mpakeni Dam, the MR14/21 and MR25 road upgrades, the Strategic Oil Reserve, a 75MW solar project, a 40MW biomass project, Manzini Mall and the new Central Bank headquarters.
Look beyond the cranes and a financial chain appears.
A CONTRACTOR WINS WORK AND BUYS MATERIALS
Those materials need transporting. Trucks need fuel. Equipment needs servicing. Workers need food and accommodation, and eventually take wages home and spend some of that money again. One project’s expenditure has now passed through several balance sheets. That is why construction growth can matter even to businesses that will never see a building plan.
For an SME, then, the opportunity may not be the multimillion-Emalangeni project itself. It may be standing one transaction away from it. You may never win a road contract. Could you supply somebody who does? What is important to remember is that the money flows in the direction of value being created.
LOOK ONE CUSTOMER AHEAD
Agriculture takes us down another road. The forecast expects a recovery, with sugarcane supported by newly irrigated land under LUSIP II and, further ahead, Mpakeni Dam’s irrigation opening the way to higher-value crops.
The obvious beneficiary is the farmer, but a stronger harvest also becomes somebody else’s transport invoice, processing contract or wage. That is also why the drought warning in the same forecast matters: under a severe drought, the statement estimates growth could fall 1.5 percentage points below the baseline in both 2027 and 2028.
Run the chain backwards. A weaker harvest can mean less product to sell, process and transport and pressure on food supply and household budgets. The weather has travelled from the sky to the balance sheet. The same connections that carry growth can carry pain.
Manufacturing is another route: the statement expects export demand for textiles, processed foods and sugar to support activity, and coal mining to gain from recovering South African demand and new Asian markets.
For an SME, that suggests a useful exercise: do not only look for your industry in the forecast. Look for your customer’s industry. Then look at your customer’s customer.
If the businesses buying from you sit close to sectors expected to expand, some of that activity may reach you. If they sit close to the forecast’s risks, that matters too.
The better question is not simply, ‘will my sales grow?’ It is: what needs to happen for my customers to have more money to spend with me? That is how to think about cash flow as a chain rather than a number.
YOUR INCOME HAS AN ADDRESS TOO
Two people can live through the same 5.3% and have completely different financial years. One works for a company winning construction contracts; another in a business seeing little change. One skill suddenly attracts demand, while another worker depends on an industry exposed to drought or weaker foreign demand.
GDP growth and personal financial progress are therefore not the same thing.
A national growth rate is an average, and an average hides more than it shows. In the first quarter of this year the economy grew by 6%; inside that number, construction grew by a third while wholesale and retail trade shrank.
The past decade says the same at length: growth averaged 2.4% a year while unemployment rose from 28% to 35%. The forecast does offer clues about the pockets where demand may develop.
Construction, agriculture, manufacturing, mining, energy and ICT all feature in the projected expansion.
So ask where your skills sit. Could a licence, a qualification or a new skill move you closer to emerging demand? Could a side business supply companies receiving more work? This is not an invitation to chase whichever sector is growing. Forecasts change. The ministry’s own forecast for 2025 was 2.3% in 2023 and 8.3% a year later; the year came in at 4.8%. It is about knowing where your income sits in the system around you.
Opportunities appear around the new spending before they appear in your salary.
Then comes the most revealing part of the forecast.
After 2027, growth slows to about 2.6% a year, partly because the big projects finish without others of the same scale replacing them. That is a drift back towards the anaemic pace of the past decade, and it should worry us.
Completing a project is not the problem. A dam is supposed to finish. So is a road.
The problem is a pipeline with nothing of the same scale behind it, and the financial test of these years begins when the building stops.
If Mpakeni’s water supports more valuable crops, construction spending has become productive capacity. If solar and biomass plants generate power at home, their value continues after the invoices stop.
If better roads move goods and people more easily, their usefulness outlives the crews.
The question is no longer how much money moved while we were building. It is what today’s growth leaves behind capable of earning tomorrow’s income.
That question travels down to us. An SME on a project should ask what remains when the contract ends. Did the good years buy equipment, build skills, win customers or create capacity that can earn elsewhere?
A worker can ask the same. A project ends; the skill learned on it travels to the next employer.
Temporary activity can leave lasting value. What matters is what we build with it.
5.3% GROWTH IS NOT IMMEDIATE MONEY IN THE BANK
One final reason not to get carried away: the forecast comes with conditions. It calls the outlook fragile, names geopolitical instability and commodity prices, including fuel, among the external risks and at home lists drought and government cash-flow pressure that could delay the capital programme behind part of the projected growth.
Follow that chain too. A delayed project means delayed work for a contractor. A supplier’s order waits. Hiring or overtime is postponed. A worker earns less than expected. The shop where that money would have been spent never sees the sale.
A cash-flow problem that began far from the shop has reached its till. That is why a forecast is not a promise.
Projects must proceed, businesses must invest, export customers must keep buying, and rain and world prices must cooperate. Growth is a chain of things going right. Break a link and the outcome changes.
So, yes, 5.3% matters. What matters more is understanding the drivers and aligning oneself with those forces. The spending behind it will move from projects into contractors, contractors into suppliers, businesses into wages and wages into shops. Some of us stand close to where that movement begins. Others meet it several transactions later. Some may barely feel it.
For a business, the task is to work out who is likely to gain customers and what they will need. For a worker, where skills are gaining value. For a household whose income depends on agriculture, construction or another exposed sector, what could interrupt the optimistic path.
The 5.3% measures the growth of the economy. Your number will be different. It will be new customers. More contracts. Higher wages. The skill that becomes more valuable. The opportunity created because somebody, somewhere, suddenly has more money to spend. The conversation about economic growth begins as a percentage. It matters to us when it is actual income.
❖ Mlungisi Ndwandwe is a seasoned strategy and investment executive with extensive experience in corporate development, capital allocation and business growth across international markets. He writes in his capacity as Founder and Chief Executive Officer of Sicebi International Group Holdings.