THE country produced less beef than it consumed in 2024, leaving an estimated 3 000-tonne gap, according to the Eswatini Competition Commission (ESCC).
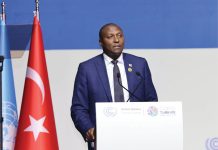
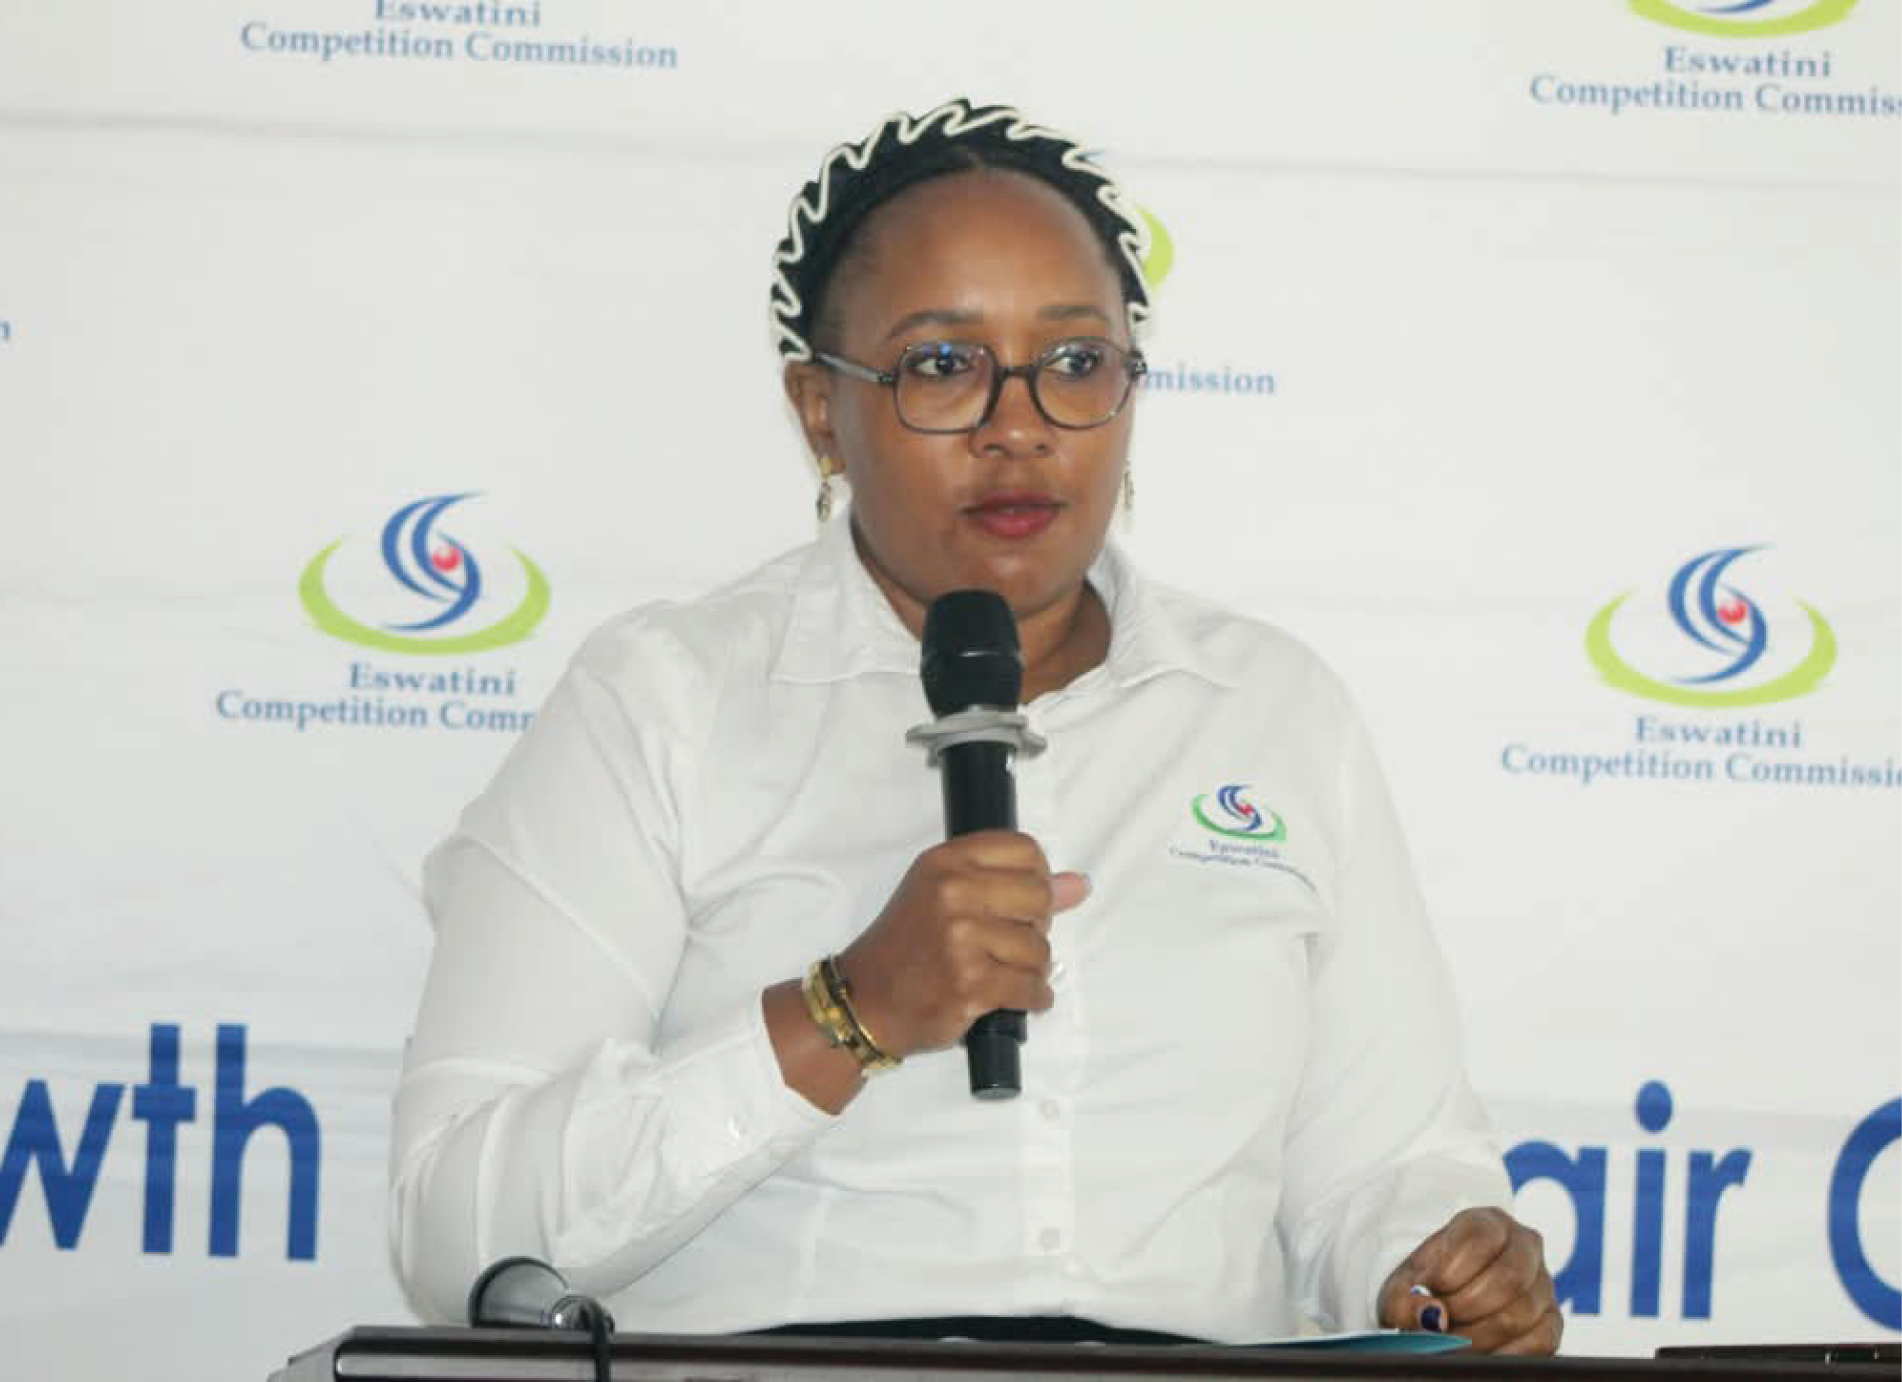
Presenting its Beef Value Chain Market Inquiry Report during a press conference at Mountain View International Hotel in Mbabane yesterday, the commission said national beef production stood at approximately 16 000 metric tonnes, against estimated consumption of 19 000 metric tonnes.
The 96-page report said imports of about 2 000 metric tonnes helped reduce the deficit, but were insufficient to meet domestic demand. The figures point to a continuing challenge for a sector that plays an important role in rural livelihoods, employment and food security.
The findings are also reflected in figures published by the Food and Agriculture Organization (FAO), which estimates annual beef demand at 19 094 tonnes and supply at 16 352 tonnes, leaving a gap of 2 741 tonnes. The FAO also puts imports at approximately 2 014 tonnes.
The ESCC described the industry as ‘operational but characterised by underlying structural weaknesses’. It identified ‘low productivity levels, limited investment in production capacity and innovation’ among the factors affecting the sector’s competitiveness.
More than 90% of cattle slaughtered through formal channels come from the communal production system, according to the inquiry. However, the report highlights constraints including overstocking, poor grazing management and vulnerability to drought, which can affect the consistency and quality of cattle supplied to the market.
The commission’s findings suggest that increasing the national herd alone may not be enough to close the gap. Improvements in productivity, breeding, animal nutrition and investment in production capacity are also important.
The ministry of agriculture identifies food self-sufficiency and sustainable agricultural productivity as key priorities in its strategic direction. The inquiry similarly points to the need for interventions that strengthen local production and improve the efficiency of the beef value chain.
The supply deficit also has implications for consumers and businesses, as limited domestic availability can increase reliance on imports. The report therefore places the challenge beyond competition between individual businesses, highlighting wider production and market constraints that affect the country’s ability to meet its own demand.
FMD shuts export doors
THE foot-and-mouth disease outbreak disrupted beef exports and complicated the country’s efforts to access lucrative international markets.
The ESCC report says the outbreak, first reported in May 2025, led to restrictions on livestock movement and the suspension of export slaughtering.
The European Union subsequently suspended Eswatini’s authorisation to export fresh beef and game meat. The EU measure took effect on June 14, 2025 following the confirmed outbreak.
The impact is significant: in 2024, Eswatini exported only 371 tonnes of beef to Norway against an available quota of 1 000 tonnes, according to the report.
The World Organisation for Animal Health (WOAH) confirmed that the country’s FMD-free status without vaccination was suspended from May 12, 2025.
Although FAO reported zero active cases in 2026, it said continued surveillance and biosecurity remain essential to restoring safe trade.
Independent farmers can’t compete
WHILE vertical integration can improve efficiency and secure supply for larger businesses, independent farmers and smaller operators risk being left at a disadvantage.
Vertical integration allows one business to operate across several stages of the beef value chain, from cattle production and slaughtering to wholesaling, processing and retailing. The Eswatini Competition Commission (ESCC) says the arrangement can improve efficiency and strengthen supply security for businesses that have the resources to operate across these stages. However, the practice may also make it harder for independent farmers and smaller businesses to compete. Integrated companies can benefit from access to their own slaughtering facilities, distribution networks and established routes to market, advantages that independent participants may not enjoy.
This can affect competition in wholesaling, where integrated businesses may distribute their own products while smaller suppliers depend on access to other buyers and facilities.
The ESCC report does not conclude that vertical integration is inherently anti-competitive. Instead, it recommends monitoring the practice to ensure that independent participants were not unfairly disadvantaged. The concern is, therefore, how the benefits of integration are balanced against fair opportunities for other players in the industry.