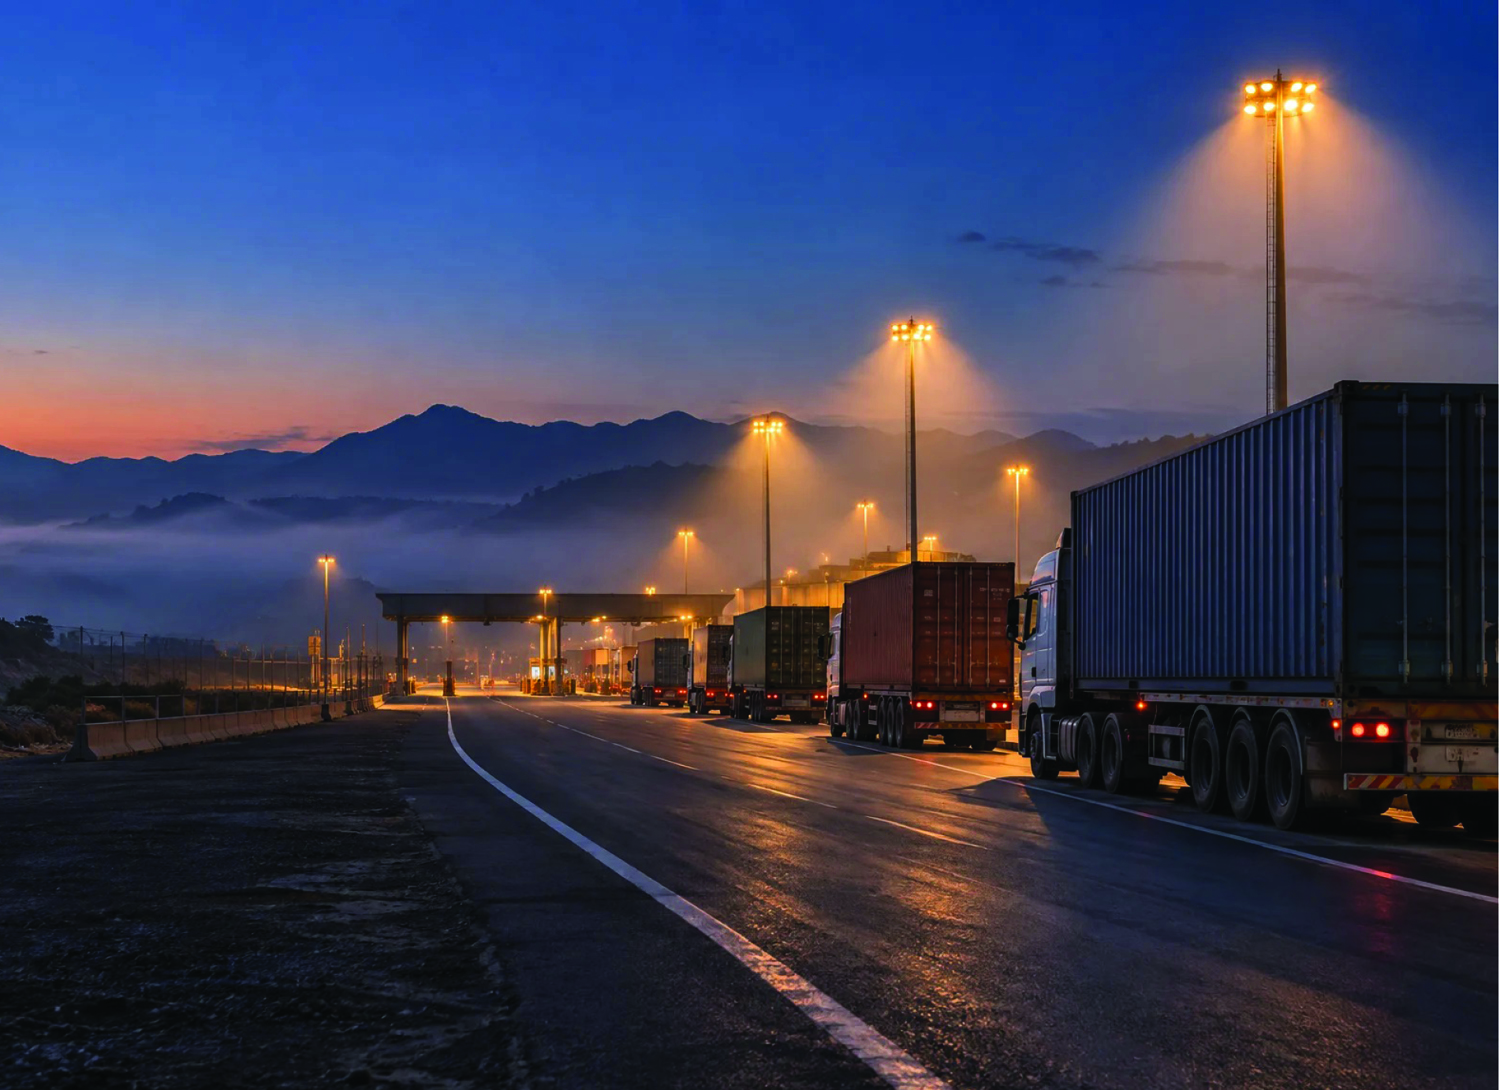
There is a good chance some of your money crossed a border this week. Perhaps it left through the fuel tank. Perhaps through groceries, medicine, a new phone or the instalment on an imported car.
You may never have seen the border post, spoken to an importer or worried about a shipping container, but part of what you earned eventually paid for something produced elsewhere.
Money travels in the opposite direction too. Somewhere beyond the kingdom, somebody buys a product made here at home. The money comes back through an exporter, which may use it to pay salaries, buy from suppliers, repay a loan or expand production. Eventually, some of it can find its way into another person’s pocket.
That is the financial story hidden inside trade. The Eswatini Revenue Service’s trade figures for August tell us that the country sold E3.86 billion worth of goods abroad and bought E3.67 billion from outside. For that month, about E194 million more came in from merchandise exports than went out on imports.
Stretch the window from April to August and the direction changes. Eswatini exported E18.25 billion but imported E19.12 billion, leaving a merchandise trade deficit of about E878 million.
That deficit was smaller than the roughly E1.02 billion recorded over the same months last year. Exports also grew faster than imports: nearly 7% against 5.6%.
A deficit in these months is not unusual. Go back through the ERS’s monthly reports and the trade balance turns out to have a season of its own. It is weakest between April and August and strongest between September and November, when sugar and chemical exports peak.
Last year’s April to August deficit had turned into a small surplus by the end of the financial year and the balance has ended the year in surplus in five of the last six.
Useful numbers. But the more interesting financial question begins after them: What happened to the money?
Consider an imported machine. The moment a local manufacturer pays E5 million for it, the purchase counts against the country’s merchandise trade balance. On the spreadsheet, E5 million has gone out.
But suppose that machine allows the factory to produce more, employ additional workers and win export orders worth E10 million over the following years. The original import has changed form.
Money left Eswatini to buy productive capacity. That capacity created output. Output generated revenue. Revenue paid salaries and suppliers. Salaries became household spending. And if some of the additional production was exported, foreign money eventually travelled back into the country.
Now spend the same E5 million importing something that is immediately consumed. Again, E5 million leaves, but there may be no productive asset left behind to generate the next lilangeni.
The two purchases look identical on today’s trade balance. They open very different possibilities for tomorrow’s economy. The real financial question is what the money leaving Eswatini leaves behind.
The August figures let us ask it of real money rather than imagined machines. The largest import line, at almost E792 million, was mineral products, which is mostly the fuel and electricity that keep trucks moving and factories running. Chemical and allied products came next at about E516 million. Machinery and electrical equipment cost roughly E371 million, prepared foodstuffs, beverages and tobacco another E366 million and vehicles and transport equipment approximately E249 million.
Now look at what left. The country’s largest export line in August was chemical products, at E1.57 billion. The second was foodstuffs, beverages and tobacco, at E1.21 billion, which is where our sugar goes. In other words, the chemicals and food we import are, to a large extent, inputs that leave again as something worth more. Machinery and vehicles together, the imports most likely to become tomorrow’s capacity, were about a sixth of the bill. The rest was consumed. These are different uses of money. We need all of them. But they do not have identical financial consequences, and the trade balance alone cannot tell them apart.
THE BILL DOESN’T STOP AT THE BORDER
There is another side to this. An importer’s bill can eventually become yours. Three weeks ago, this column followed a dry summer from the farm gate to the till. Imported prices travel the same road.
If fuel becomes substantially more expensive internationally, a transport company needs more money to run the same truck over the same distance. It can absorb the increase and sacrifice some margin or eventually charge its customers more. The supermarket then pays more to receive stock, and the shock arrives at your house as another E100 at the filling station or a grocery basket that no longer fits as comfortably inside the same salary. You do not have to import anything yourself to have your finances exposed to the rest of the world.
WHERE THE MONEY COMES FROM
Exports carry money in the opposite direction. When an Eswatini business sells E1 million worth of goods abroad, some of that revenue may pay employees, suppliers and transporters. Some may service debt, finance another machine, become profit or eventually become tax.
The employee then spends a salary. The supplier pays its workers. The transport company repairs a truck. One export order can create several financial relationships at home.
That is why the near 7% growth in exports between April and August matters beyond the companies doing the exporting. The deeper question is how much of that export income continues working inside Eswatini.
An exporter that buys locally, employs locally and reinvests locally gives foreign demand more routes through the domestic economy. A lilangeni earned abroad becomes more valuable at home when it creates another productive transaction here.
Where that money comes from also matters. In August, 96% of the country’s merchandise exports went to Africa. Nearly three quarters of what we sold, E2.83 billion of the E3.86 billion, went to our partners in the Southern African Customs Union. In the same month, SACU supplied seven in every ten emalangeni of what we bought.
There are obvious advantages to having large markets close to home. Regional integration connects supply chains and gives local companies access to customers beyond the kingdom’s small domestic market.
Financially, however, concentration also connects our fortunes. If demand weakens in an important regional market, a local exporter’s order book may feel it first. Fewer orders can become less revenue. That can become reduced overtime, postponed recruitment or smaller purchases from suppliers. Then the supplier loses revenue too.
The relationship works in our favour when regional demand strengthens. Economic integration gives us access to our neighbours’ prosperity, but it also gives their problems a road into ours. Diversification, viewed this way, is not merely trade policy. It is risk management.
SMES IN THE MIDDLE
For a small business, these enormous trade numbers can become a very ordinary cash-flow problem.
Suppose a retailer normally needs E100 000 to restock. Supplier prices and transport costs rise 10%. Filling the same shelves now requires E110 000. The business has not grown. It has not bought more stock. It needs another E10 000 simply to stand still. The owner must find that money somewhere: cash reserves, supplier credit, a smaller order, borrowing or higher prices.
This is how an external shock becomes a working-capital problem. A business can remain profitable on paper and still struggle for cash because more money is required to replace the same stock.
For an SME owner, knowing where stock and inputs come from is therefore part of knowing the financial risks inside the business.
But imports also contain opportunity. If Eswatini repeatedly spends substantial amounts buying something from elsewhere, that tells an entrepreneur something important: demand already exists.
It does not mean every import should be replaced locally. Producing something here for E150 when it can reliably be imported for E100 merely to reduce the import bill would make little financial sense.
The smarter question is whether part of that value chain can competitively happen here. Perhaps it is not manufacturing the entire product. It might be packaging, repairing, supplying an input, providing transport or processing something further before it leaves the country. For an entrepreneur, the import bill can therefore become a map of where customers are already spending money.
WHAT IT MEANS AT HOME
For households, the lesson is not to start studying customs tables before going grocery shopping. It is to recognise that part of your financial life is exposed to things you cannot control. Your salary can remain exactly the same while the cost of imported necessities changes around it. That makes the margin in your budget important, and it is the same margin an SME needs in its working capital and a country needs in its productive capacity and its spread of markets. Each has more ways to adjust when conditions outside its control change.
And that brings us back to the kingdom’s E878 million merchandise trade deficit. Is it good or bad? The number alone cannot tell us. It tells us that between April and August, the country bought about E878 million more merchandise from abroad than it sold. It does not tell us whether that money bought productive machinery or immediate consumption. It does not tell us how much value exporters created locally before their products left. And five winter months do not tell us how the year will end.
A country does not become financially stronger merely by preventing money from leaving. Money is supposed to move.
The question is what that movement builds. Can machinery imported today increase production tomorrow? Can more local SMEs supply larger exporters? Can products be processed further here before crossing the border? Can businesses find more customers beyond the markets on which we already depend?
The challenge is not to stop money leaving Eswatini. It is to give more of it a reason to work here first.
So the next time billions of emalangeni appear beside imports and exports, follow the money beyond the headline number. Ask what we bought with it. What we produced with it. How much value we added to it. And whether, somewhere along the journey, it created another income, customer, business or productive asset. Because, as we asked of borrowed money a few weeks ago, what matters is not simply how much money crosses our borders. It is what the money leaves behind.
MLUNGISI NDWANDWE is a seasoned strategy and investment executive with extensive experience in corporate development, capital allocation and business growth across international markets. He writes in his capacity as Founder and Chief Executive Officer of Sicebi International Group Holdings.