THE country’s payment landscape is entering a new phase as banks and mobile money providers become connected through a national payments platform.
The full activation of the Eswatini Payment Switch (EPS) fast payments platform marks a major shift in how businesses and individuals move money, with transactions now able to flow between different financial service providers in real time.
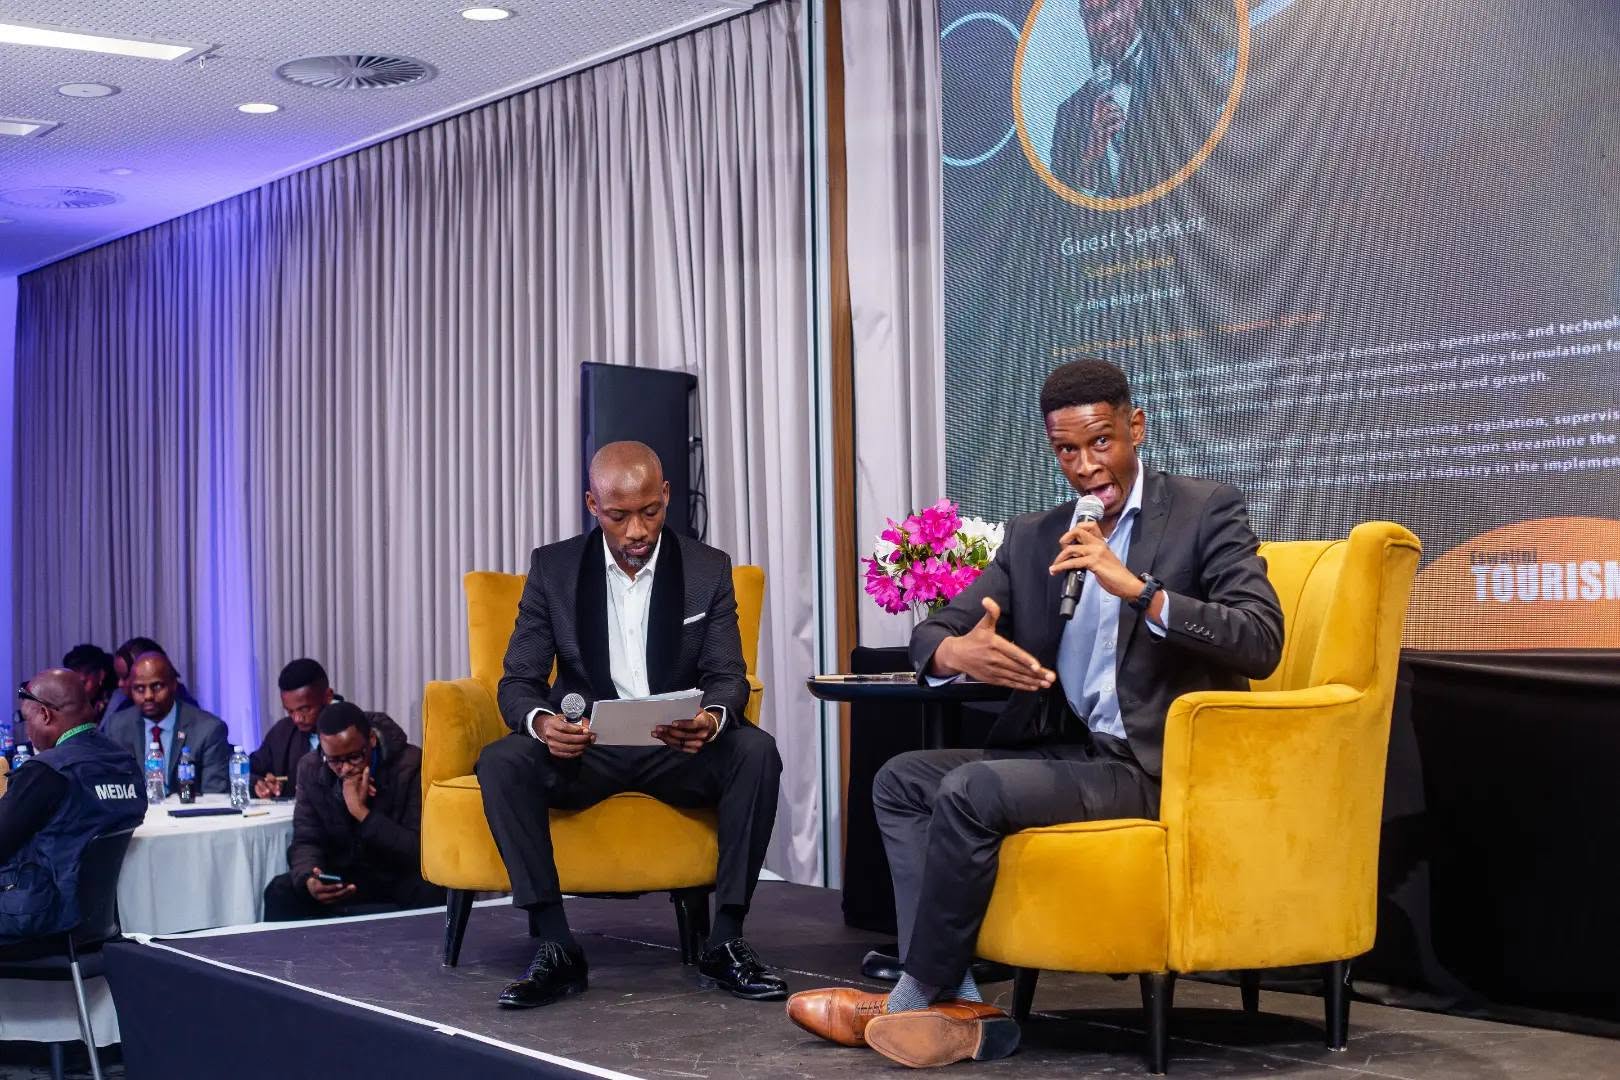
Speaking during Tourism Nkwe 2026 at the Hilton Garden Inn in Mbabane, Central Bank of Eswatini (CBE) Deputy Director Operations – Payment Systems Sabelo Gama said the switch represented a broader payments infrastructure rather than a single product.
“The switch is a big, broad platform,” Gama said. “Consider something like Samsung, for instance, that is the company. The company releases products. That can be a TV or a fridge. So if you consider the switch is the company, we have deployed a first product called fast payments.”
Fast payments allows customers to transfer funds between participating banks and mobile money service providers without being restricted by where their accounts are held. The CBE has described the EPS as an initiative aimed at improving interoperability between banks and non-bank payment providers while supporting digitalisation and financial inclusion.
For businesses, particularly small and medium enterprises (SMEs), the change could improve how quickly they receive customer payments and settle transactions with suppliers.
Gama explained that the platform operates continuously, allowing payments to take place beyond traditional banking hours.
“This payment, as in moving money, whether bank to bank, bank to mobile money, happens 24/7. Weekends, any time, holiday, the money moves,” he said.
The development also addresses a long-standing challenge in the local payments ecosystem — fragmented payment channels where customers using different providers may experience barriers when transferring funds.
The next stages of the payments infrastructure are expected to introduce additional capabilities, including QR code payments, open banking and domestic card switching.
The CBE has previously indicated that these modules are designed to enhance payment efficiency, improve customer experience and enable wider digital payment adoption.
Gama said the immediate focus remained on expanding practical payment solutions that can be used by businesses and consumers.
“What we are working on at present with the industry is what we call QR code payments,” he said.
As a result, businesses are likely to see new opportunities to receive payments, manage cash flow and serve customers through different digital channels.
Digital payments to benefit tourism
HOTELS, tour operators and small vendors stand to benefit as the kingdom expands digital payment options.
As tourism businesses increasingly serve visitors who expect electronic payment options, improved payment infrastructure could become an important part of the sector’s growth.
Central Bank’s Sabelo Gama said the payment switch creates the foundation for wider digital payment services, although the immediate focus remains domestic transactions.
“The initial focus of the switch is on domestic transactions,” he said.
He added that future development would involve connecting with other countries.
For tourism SMEs, the potential lies in having more convenient ways to accept payments from local customers while preparing for broader digital payment integration.
Furthermore, the bank indicated before that the payment switch is intended to support digital products, financial inclusion and future connections with e-commerce platforms.
The next challenge for businesses will be adapting to these tools and ensuring customers understand how to use them safely and effectively.
From cash to QR code for SMEs
SMALL businesses could soon accept digital payments through simple QR codes, reducing reliance on cash and expensive payment equipment.
A new payment tool being developed under Eswatini’s payment switch could change how small businesses receive money from customers.
Central Bank of Eswatini (CBE) Deputy Director Operations – Payment Systems Sabelo Gama said QR code payments would build on the existing fast payments platform by giving merchants a simpler way to accept digital payments.
A QR code, or quick response code, is a square-shaped barcode that can be scanned using a smartphone. Once scanned, it can direct a payment from a customer’s banking application or mobile wallet to a merchant’s account. Gama explained that the technology could be particularly useful for smaller businesses.
“A QR can be printed. That’s one type of QR,” he said. He said a market trader could register with a financial institution, receive a QR code and allow customers to pay digitally by scanning it with their phones.
“Fast payment connects everything in our market,” Gama said. “So now this market seller can register with a bank, have a QR code issued to them and receive digital payments.”
For SMEs, the benefit could provide greater access to digital payments without necessarily requiring traditional point-of-sale machines.