Last week, this column pictured a widow who feeds three grandchildren on her E600 grant.
Her son is 28. He finished school and has no work. Say he finds a job at 30, on E4 000 a month. By law, E400 goes into his provident fund, half of it from his pay. Another E400 goes to his mother’s house.
When an unexpected medical bill arrives, he sends whatever he can.
Perhaps there ought to be a kinder name for the so-called black tax he pays. In many families, this is how one generation helps the next find its feet.
Parents go without so their children can study. Older siblings help younger ones through school. Whoever finds work first does the same for the relatives still waiting.
This sense of duty is rooted in Ubuntu, the belief that our wellbeing is bound to that of others. In our society, a person’s success is seldom theirs alone.
‘Tax’ is a harsh word for that solidarity. Still, the so-called black tax names something real: the unwritten bills working people carry for parents, siblings and extended family.
Unlike income tax, this deduction has no rate, no assessment and, often, no end date. The amount depends on who needs help, how badly, and who earns enough to respond. That money has paid school fees and hospital bills in many homes. It can also leave the earner struggling to build any security of their own. The bills come from old gaps: too few jobs and too little family wealth to give the next generation a start. The 2023 labour survey counted nearly 200 000 people aged 15 to 35 neither working nor studying. The son, still jobless at 28, is one of them. In 2025, fewer than four in ten people aged 25 to 29 had a job.
ONE SALARY, TWO HOUSEHOLDS
Back to the son at 30. Every month, E400 goes to his mother’s house and E200 to the three grandchildren’s school costs. Another E100 covers whatever comes up, averaged over the year. That is E700, more than a sixth of his pay. It goes out before his own rent, food, transport and debt. Over a year, the E8 400 comes to more than two months’ wages. One E4 000 salary is now paying for two households: his mother’s and the one he hopes to start. And unlike the bank, the family does not send a statement showing the outstanding balance.
In October this column found that three in 10 adults would turn first to family or friends for emergency money. The son is who they call. The pressure also runs the other way.
Elderly parents are asked to raise grandchildren whose parents may or may not be living, on a meagre E600 a month. Some children, many of them orphaned by AIDS, head their own homes and survive on the kindness of neighbours. Often there is no one else.
Until the son finds work, his mother carries her house alone. She spent her working years without a pension. When another relative faces a medical bill the household cannot absorb, the earner becomes the family’s safety net, standing in for savings, insurance and public support.
When one salary covers every shortfall, the family may slowly organise its finances around it. A temporary contribution towards school fees becomes a standing monthly transfer. Assistance with groceries becomes an expectation. An emergency request becomes hard to tell from an ordinary expense.
Nobody intends to exploit anyone. Each request makes sense on its own. Trouble starts when they add up to a commitment the earner cannot keep.
A flat refusal may protect one budget and create a crisis in another. How can a family keep the benefits of mutual support without one member carrying everyone? A bucket carried with good intentions can, over time, become a burden that is hard to put down. Yet putting it down can cause fractures in the same family we mean to keep intact. The other risk is that the carrier’s financial pressure could metastasise into pain and resentment.
WHAT THE MONEY COSTS
Suppose the son pays E700 a month from 30 to 45, until the children finish school. Say he had saved it instead, at an illustrative 7% a year, compounded monthly. By 60 it would be worth about E632 000. He would have paid in E126 000. His provident fund, untouched from 30 to 60, would hold about E488 000. The 7% is an assumption and inflation would shrink both figures. Of course, a parent who needs groceries cannot eat compound interest.
Sometimes an immediate family need rightly comes first. The trade-off is rarely the problem. More often, the commitments creep up before any plan is in place. Or they drag on because no one looked for a more lasting way out.
The danger is what the E700 crowds out. With nothing set aside, the next medical bill becomes a loan. At 50 the provident fund pays out in full, and it clears what he has borrowed. He reaches 60 with too little to live on. The grandchildren he helped through school now carry him.
PUT A NUMBER TO GENEROSITY
The fix begins with something unromantic: a budget. In September this column argued for deciding what comes first. Family support needs the same treatment. Start with housing, transport, food, debt repayments and insurance. At minimum, add a realistic amount for emergency savings and retirement.
Only then decide how much you can send, month after month. That way the latest request does not set the whole month’s budget. Suppose the son’s budget says he can afford E500 a month. Make that his plan. A steady E500 beats an E700 promise he has to borrow to keep. The school money stays, because it buys the family its next earner. That leaves E300 for the house, down from E500. He is the only earner in his mother’s house, so the missing E200 is a conversation with her. They decide together what can wait and which relatives might help.
That conversation may be uncomfortable. So is explaining to a landlord why the rent is late. In families with several working siblings, a shared plan is fairer than leaving it all to whichever child gets the most phone calls.
Contributions need not be equal. At 10% each, a sibling on E8 000 gives E800 and one on E30 000 gives E3 000. On E700 the son was giving 17.5%; even on E500 he gives 12.5. A stokvel already shows how to share: everyone pays in on the same day and everyone sees the book. The family should know who pays, what it covers and whether it is still affordable.
Separate a once-off need from an ongoing one. Paying E1 000 towards his mother’s medical bill is different from paying E1 000 every month. Both may be right, but they need different decisions. For a once-off emergency, ask what is needed, by when, and who else can help.
For recurring support, agree on the amount, purpose and how long it lasts. Borrowing to give turns one obligation into two: the family expense and the loan repayment.
A bank does not charge less interest because the loan was for a good cause. Pay the rent and the loan instalment before family support.
HELP THAT CHANGES SOMETHING
Before sending money, ask one more question: will this ease a problem for now, or stop it coming back? Food, medicine and household bills must be met. Beyond them, the most useful support may be training, help to finish a qualification or careful start-up money for a small business. The son’s E200 for the grandchildren’s school is that kind of money.
A business can fail, and training does not guarantee a job. Help should not come with impossible conditions either. Some help can come from outside the family. Today, at 28 and out of work, the son is exactly who the Eswatini Youth Employment Opportunities Project is for. It aims to reach about 30 000 people aged 18 to 35 who are out of work, school or training. It offers training, apprenticeships and start-up support in farming, agribusiness and the building trades. Applications close on Friday, November 13.
Forms are at the nearest Inkhundla centre. If he would rather start a business, the Youth Enterprise Revolving Fund lends to young people. There are few such doors.
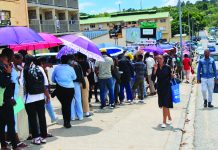
The project’s 30 000 places sit against nearly 200 000 young people out of work and school, roughly one place for every seven. In 2025 the World Bank estimated about 1 000 new jobs a year for 25 000 new job seekers. That is one job for every 25 people looking. A family plan can share the bill; only jobs make it smaller. This week thousands of young people queued at police headquarters in Mbabane, Manzini, Siteki and Nhlangano, some from midnight, for a limited number of constable posts.
The son could have been in it. That queue said more about where our efforts belong than a thousand speeches or columns could.
NEVER SAYING ‘ENOUGH’ HAS A PRICE
Much is asked of whoever earns first, however little the job pays. None of this means abandoning the people who helped us become who we are. There is dignity in looking after ageing parents and in helping a sibling finish school. Support lasts when it protects the person paying for it.
The overused aviation metaphor of ‘put on your mask first’ applies. It means letting the earner build a home, raise children and save for retirement. Now and then, they may spend on themselves without it counting against the family.
Perhaps that is why the so-called black tax still sits uneasily as a name. It names the pressure and misses the solidarity behind it. The best return on the son’s E200 for school comes on the day one of those grandchildren starts sending money home too. Better still is the day they send it by choice, with no fire to put out.
g Mlungisi Ndwandwe is a seasoned strategy and investment executive with extensive experience in corporate development, capital allocation and business growth across international markets. He writes in his capacity as Founder and Chief Executive Officer of Sicebi International Group Holdings.